Author Archives: ICLMG CSILC

Submission to UN Special Rapporteur: National security, counterterrorism and systemic racism and Islamophobia in Canada

In late September, the UN Special Rapporteur on contemporary forms of racism, racial discrimination, xenophobia and related intolerance, Dr. Ashwini K.P., visited Canada to meet with stakeholders and government officials to evaluate Canada’s efforts to counter racial discrimination. ICLMG had the opportunity to meet with Dr. Ashwini along with other non-governmental organizations, activists and academics to share our analysis. Following the meeting, we submitted a brief for the Special Rapporteur’s study, which will result in a full report delivered at the 65th session of the Human Rights Council in June 2027.

Below is an excerpt, a summary of our recommendations and a link to the full brief.


National security, counterterrorism and systemic racism and Islamophobia in Canada

As a broad-based coalition deeply concerned by the impacts of all forms of hate and racism in Canada, we are pleased to submit this brief to the UN Special Rapporteur on contemporary forms of racism, racial discrimination, xenophobia and related intolerance regarding the impacts of Canada’s anti-terrorism and national security laws.

Our coalition’s focus is on the impacts of national security and anti-terrorism laws in Canada, and our country’s role and actions post 9/11, throughout the so-called War on Terror, and the evolving views on terrorism, extremism and violence today.

We have documented, criticized and proposed solutions to the negative impacts that these laws have had on freedom of speech, association, religion and movement; on privacy; on levels of government surveillance; on the rule of law; on due process and access to justice; and on equality rights.

Throughout all this, we have also seen a deeply problematic and consistent problem of racial, religious and political profiling, abetted by the vague and overreaching definitions of terrorism and national security. Central to this has been the targeting of Muslims, Arabs, and those perceived to be Muslim, although it has also deeply impacted other communities, most notably Indigenous peoples as well as environmental and climate activists.

This undue focus on the so-called “Islamist” threat, espoused even by a former prime minister as being the “greatest” threat to Canada, has led to more than two decades of state-sanctioned, systemic racism against Muslims and other racialized communities in Canada.

Much needs to be done to address individual acts of hatred and Islamophobia; however, the role of state systemic Islamophobia must also be clearly and immediately addressed. And while the response to “individual” vs. “systemic” Islamophobia may take different shapes, it is crucial to recognize how one supports the other. Decades of government agencies and officials framing Muslims in Canada and internationally as being the most direct threat to national security – despite a lack of evidence demonstrating that threat, and in ignorance of other more direct threats such as the horrific treatment of Indigenous peoples, the threat of climate change, and increasingly the threat of white supremacist violence – have fed the fears of the public, causing individuals to view their Muslim neighbours and colleagues with fear and suspicion.[1]

Over the past two decades, studies by academics and civil liberties organizations have repeatedly documented the disproportionate impact of national security measures on Muslim communities. Laws like the Anti-Terrorism Act, 2015[2] and the National Security Act, 2017[3] have expanded national security powers without adequate transparency and oversight, disproportionately threatening the fundamental rights and freedoms of communities across Canada. While Muslim communities have faced some of the most direct impacts, the intersection of municipal and provincial policing, federal policing and intelligence agencies means that the impacts have been felt more widely, including the growing use of facial recognition and other algorithmic policing tools that are known to be biased against people with darker skin tones, and especially Black and Indigenous women; the framing of South Asian and Indian migrants, among others, are either national security or terrorist threats; the use of national security measures to criminalize and repress Indigenous land defenders; and the targeting of Palestinians, especially those advocating against the genocide and for Palestinian self-determination and human rights as terrorist threats.

In our report we identify several areas of concern that require urgent action that we hope will assist in the Special Rapporteur’s research and upcoming report on Canada. Below you’ll find our recommendations for each area of concern. To read the full report, click here.

Areas of concern and recommendations

1. Surveillance and algorithmic policing

Recommendations:

  • That Canada adopt transparent, rigorous and independent human rights evaluation of new surveillance and algorithmic policing tools before adoption
  • That Canada review national security and counter-terrorism legislation through an anti-racist, intersectional and anti-oppressive lens
  • That Canadian law enforcement and intelligence agencies end their targeted surveillance of racialized communities

2. Civil society organizations and NPOs

Recommendations:

  • That the Ministry of Finance revisit the anti-terror regulatory, policy and legislative landscape, particularly the 2015, 22023 and 2025 National Risk Assessments and their impacts, particularly on the Muslim community.
  • That the Minister of National Revenue declare an immediate moratorium on the targeted audit of Muslim charities by the CRA RAD until such a review is completed and legislative changes put in place
  • Integrate civil liberties and financial inclusion impact analyses into National Risk Assessments (NRA).
  • Issue policy guidance to relevant departments and bodies on de-risking and financial inclusion, including reporting requirements.
  • Amend the PCMLTFAto require reporting entities to report annually on de-risking, including volumes and rationale.
  • Amend the PCMLTFAto clarify that failing to safeguard against disproportionate de-risking constitutes a compliance failure.
  • Develop training on risk-based decision-making regarding the NPO sector, including systemic bias and discrimination.
  • Allow independent review of financial institutions’ risk-based decision-making in complaint investigations.

3. Border controls

Recommendations:

  • That Canada establish an independent complaints and review body for the Canada Boder Services Agency
  • That Canada amend the provisions of the Strengthening Canada’s Immigration System and Borders Act to prevent discretionary decision-making, protect privacy and uphold the rights of refugees
  • That Canada withdraw the immigration security certificates against Mr. Harkat and Mr. Mahjoub, and repeal the security certificate system
  • That Canada abolish its secretive, discriminatory No Fly List regime

4. Terrorist Entities Listing

Recommendation:

  • Canada should rescind the Terrorist Entities Listing process in favour of transparent, targeted sanctions.

5. Canadian complicity is detention, mistreatment and torture abroad

Recommendations:

  • Resolve the case of Abousfian Abdelrazik and apologize for the Canadian government’s role in his mistreatment.
  • Take action to safely repatriate all Canadians currently detained in Northeastern Syria and Iraq.
  • Commit to no new extradition of Dr. Diab to France.

6. Dissent and free expression

Recommendations:

  • Canada must stop considering all Palestinians as potential security threats, welcome the Gazan families of Palestinian Canadians accepted through the “emergency” program, and reopen the program to process more applications to save more lives before it’s too late.
  • The federal government must ensure law enforcement and intelligence agencies halt their targeted surveillance and criminalization of Muslim, Palestinians and their allies.
  • Canada must significantly amend the Combatting Hate Act to remove provisions that impinge on freedom of expression and assembly, and that can be used in discriminatory, arbitrary ways.

7. Combatting hate online

Recommendations:

  • Remove the definition of content that incites terrorism or violent extremism from Bill C-34, the Safe Social Media Act.
  • Ensure a clear and effective redress mechanism for instances when social media platforms engage in overcompliance/censorship as a result of online harms regulations.

8. Review and accountability

Recommendation:

  • That the federal government restore funding cuts to NSICOP, NSIRA and IC, and engage in consultations to increase their funding to be commensurate with their work to oversee Canada’s national security regime.

[1] “Islamophobia in Canada: Submission to the UN Special Rapporteur on Freedom of Religion or Belief” (30 Nov. 2020) International Civil Liberties Monitoring Group, Islamic Social Services Association, and Noor Cultural Centre. Online: https://www.ohchr.org/Documents/Issues/Religion/Islamophobia-AntiMuslim/Civil%20Society%20or%20Individuals/Noor-ICLMG-ISSA.pdf

[2] Anti-terrorism Act, 2015 (S.C. 2015, c. 20), https://laws.justice.gc.ca/PDF/2015_20.pdf

[3] National Security Act, 2017 (S.C. 2019, c. 13), https://laws-lois.justice.gc.ca/eng/acts/N-16.56/

Since you’re here…

… we have a small favour to ask. Here at ICLMG, we are working very hard to protect and promote human rights and civil liberties in the context of the so-called “war on terror” in Canada. We do not receive any financial support from any federal, provincial or municipal governments or political parties. You can become our patron on Patreon and get rewards in exchange for your support. You can give as little as $1/month (that’s only $12/year!) and you can unsubscribe at any time. Any donations will go a long way to support our work.panel-54141172-image-6fa93d06d6081076-320-320You can also make a one-time donation or donate monthly via Paypal by clicking on the button below. On the fence about giving? Check out our Achievements and Gains since we were created in 2002. Thank you for your generosity!
make-a-donation-button

The Damage of De-risking: How Canada’s Policies to Counter Terrorism Financing Drive Financial Exclusion

After months of work, we are pleased to publish our latest report: “The Damage of De-risking: How Canada’s Policies to Counter Terrorism Financing Drive Financial Exclusion.”
Read the Executive summary below or in PDF format here

Read the full report here

Watch the recording of our launch event with ICLMG’s National Coordinator and report author, Tim McSorley, in conversation with Canada’s former Special Representative on Combatting Islamophobia, Amira Elghawaby

Acknowledgements

This report benefited greatly from a multitude of conversations, meetings, emails and discussions with members of the NPO sector, particularly those working in humanitarian aid and within Muslim communities. We are grateful for their insights, support and generosity of time and knowledge.

We are also very grateful for the support of The Muslim Fund, whose financial support made this project possible.


Executive Summary

  • The Policy Architecture Behind De-risking
  • Documented Patterns and Impacts
  • Recourse, Oversight, and Accountability Gaps
  • Summary of Case Studies
    • Case 1: Impact on Funding
    • Case 2: The Role of Implicit Bias in De-banking Decisions
    • Case 3: Disconnect Between De-risking and Government Sanctions Lists
    • Case 4: Collateral Damage to Families and Financial Ecosystems
    • Case 5: Opaque Internal Practices of AML/ATF Compliance Units
    • Case 6: Impact on Donors
  • Summary of Recommendations
    • For the Government of Canada
    • For Supervisory Bodies
    • For Financial Institutions and Payment Processors

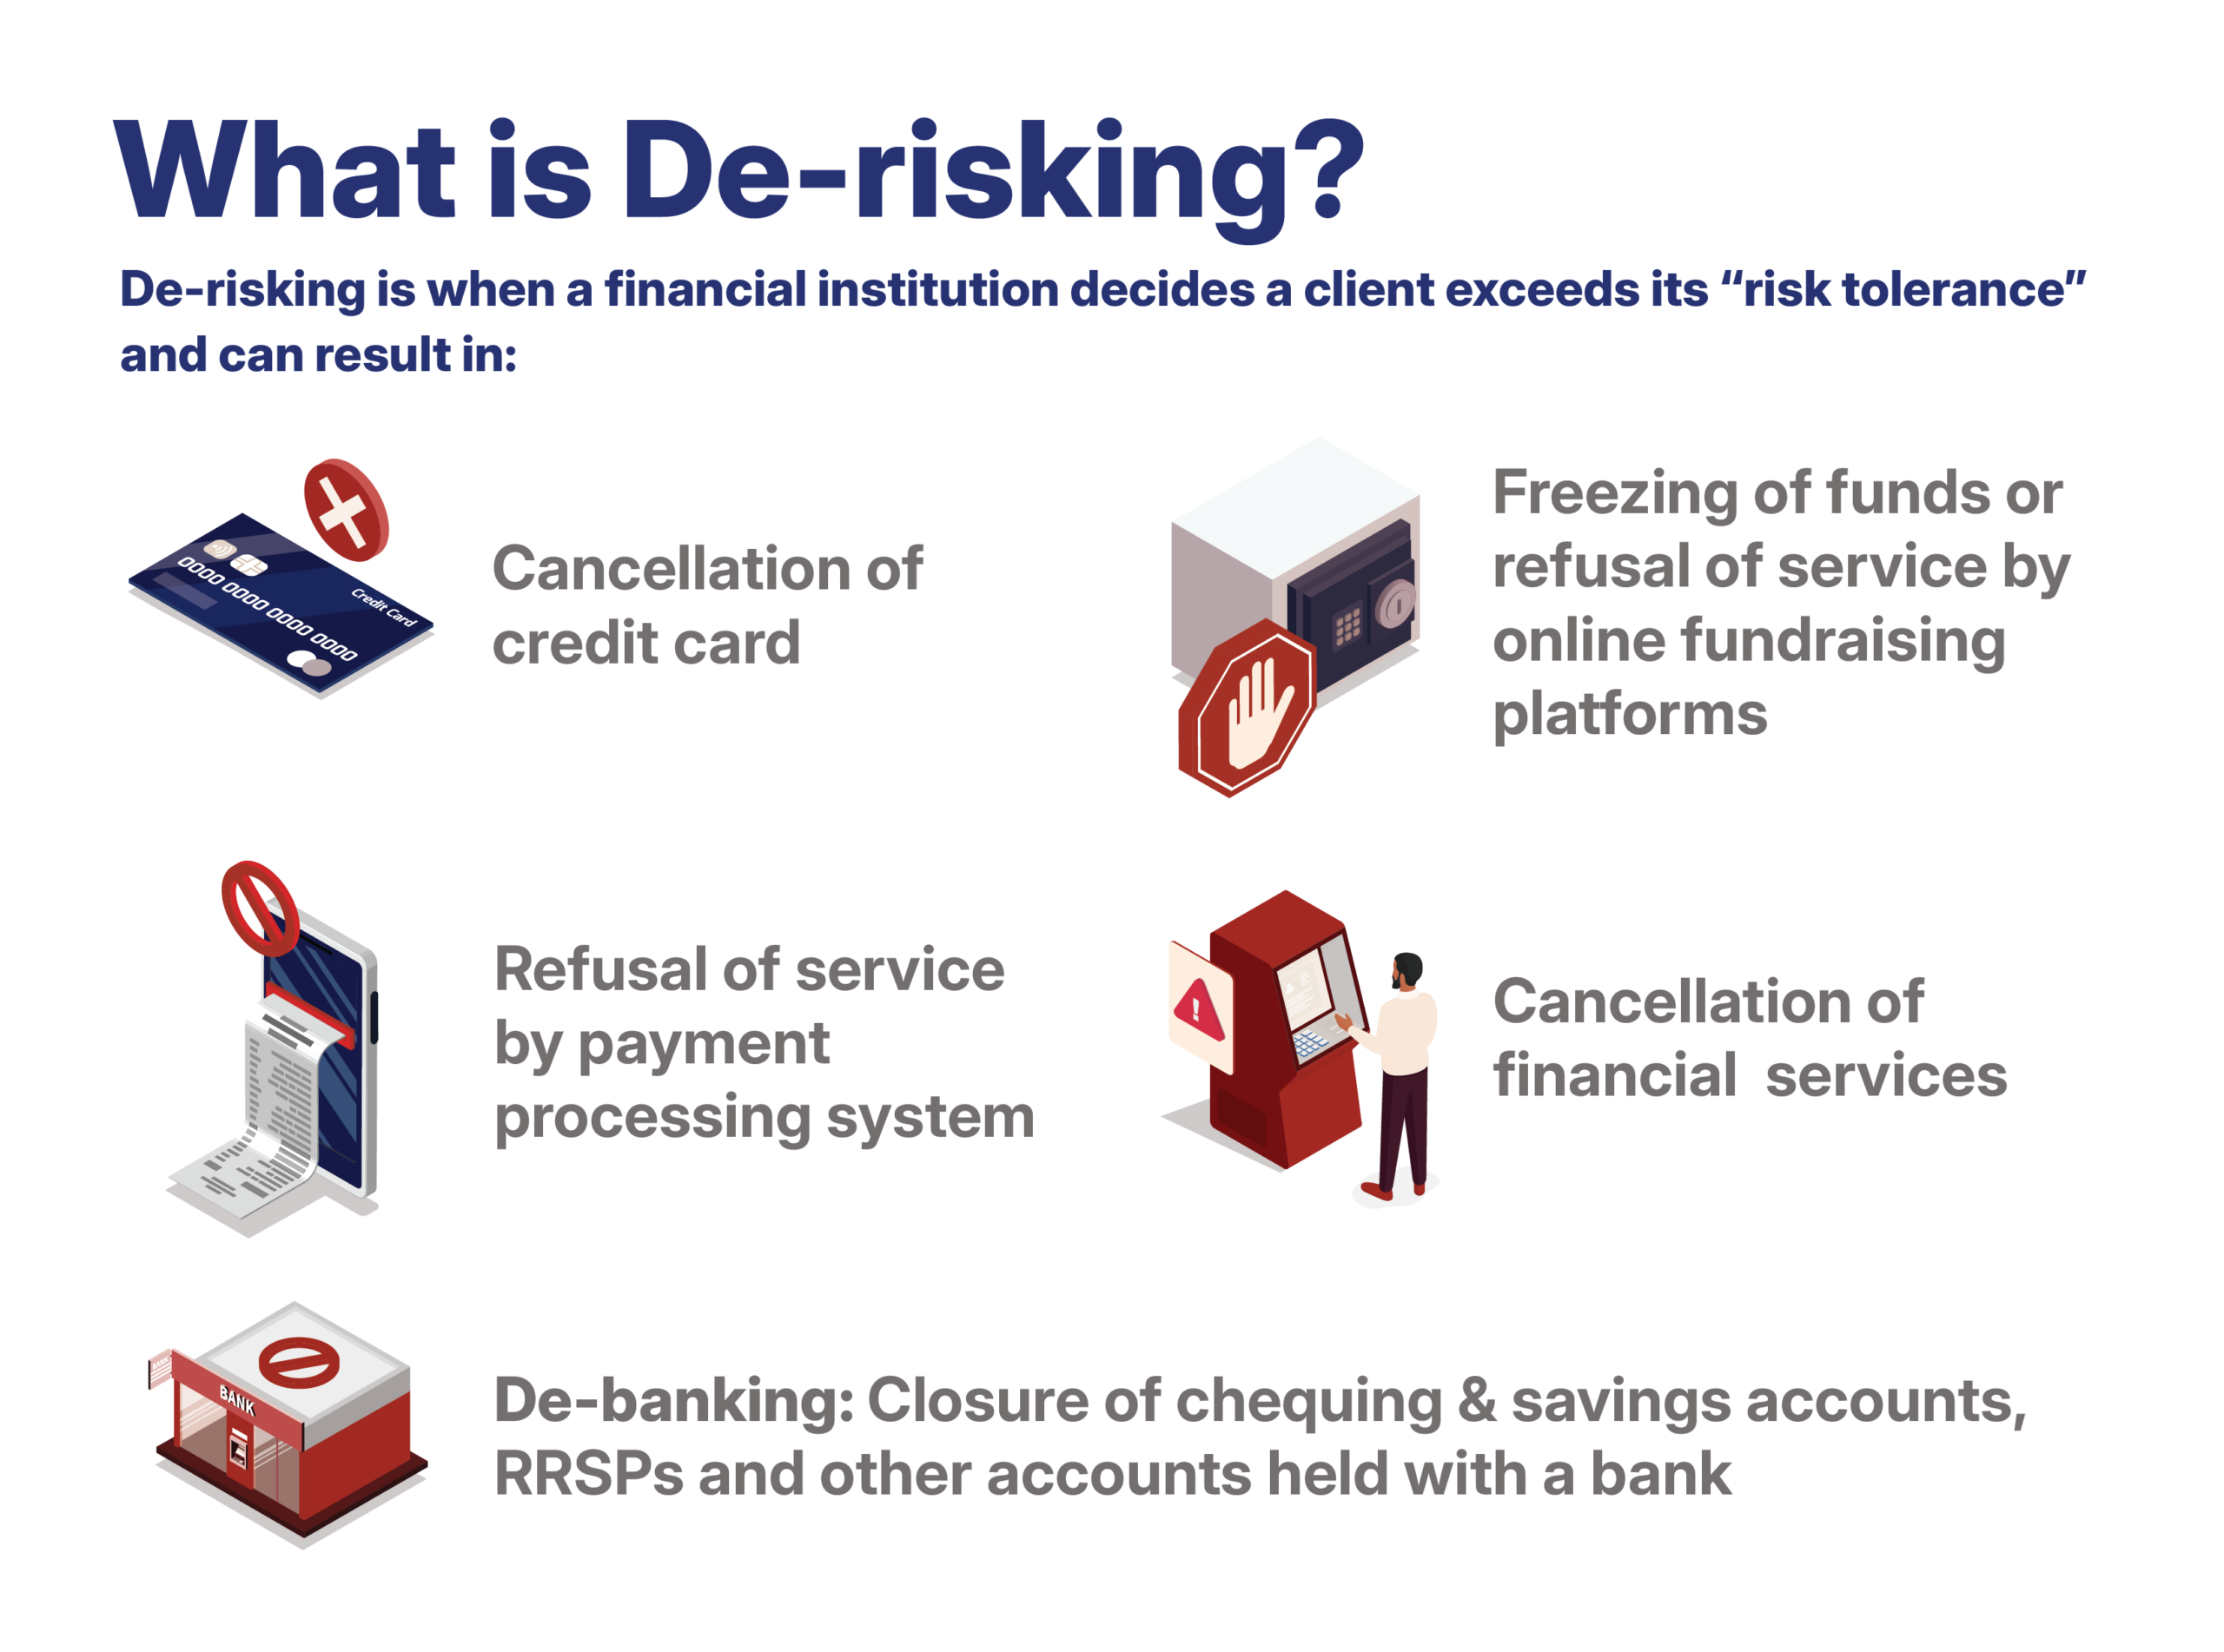
De-risking refers to the practice whereby financial institutions terminate or restrict access to financial services for certain clients or sectors in order to avoid perceived regulatory, compliance, or reputational risk, rather than managing that risk through proportionate, individualized and evidence-based mitigation measures. This lack of individualized and evidence-based decision making has resulted in unjustified and discriminatory decisions that significantly impact both individual and organizational clients, including non-profits and charities. This report demonstrates that the de-risking of non-profit organizations (NPOs) in Canada, particularly those that are active in Muslim communities or carrying out humanitarian activities abroad, is not a series of isolated commercial decisions made by individual banks, but a predictable structural outcome of Canada’s anti-money laundering and anti-terrorist financing (AML/ATF) framework.

Severe penalties for non-compliance, ambiguous risk standards, overbroad sector-level risk signaling, and opaque decision-making incentives have created an environment where financial institutions either prioritize or are pushed toward risk avoidance rather than risk management. As a result, charities and civil society organizations, particularly Muslim-led organizations and those engaged in humanitarian or international assistance, are reporting de-risking incidents that appear to be based on risk avoidance rather than individualized assessment, raising serious questions of discrimination, profiling, disproportionate impact and unintended consequences.

The analysis is grounded primarily in publicly available sources, including Canadian legislation, national risk assessments, parliamentary studies, oversight body findings, and government strategy documents, supplemented by anonymized case material shared by affected organizations and individuals. While comprehensive quantitative data on de-risking in Canada does not exist, this absence is itself a critical finding: it reflects systemic opacity, commercial confidentiality, and the absence of regulatory requirements for transparency or reporting. The public record alone is sufficient to identify the policy design flaws that enable and sustain de-risking.

This report builds directly on ICLMG’s 2021 report, “The CRA’s Prejudiced Audits,” which documented the disproportionate national security scrutiny of Muslim charities and helped catalyze reviews by the Office of the Taxpayers’ Ombudsperson (OTO), the Senate of Canada, and the National Security and Intelligence Review Agency (NSIRA). De-risking is presented here as the downstream, private-sector manifestation of the same structural problems identified in that earlier work.

The Policy Architecture Behind De-risking

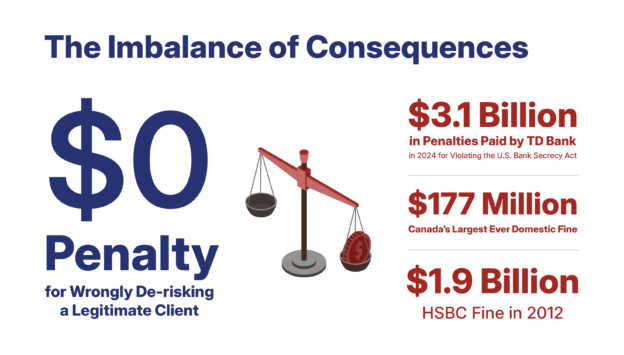
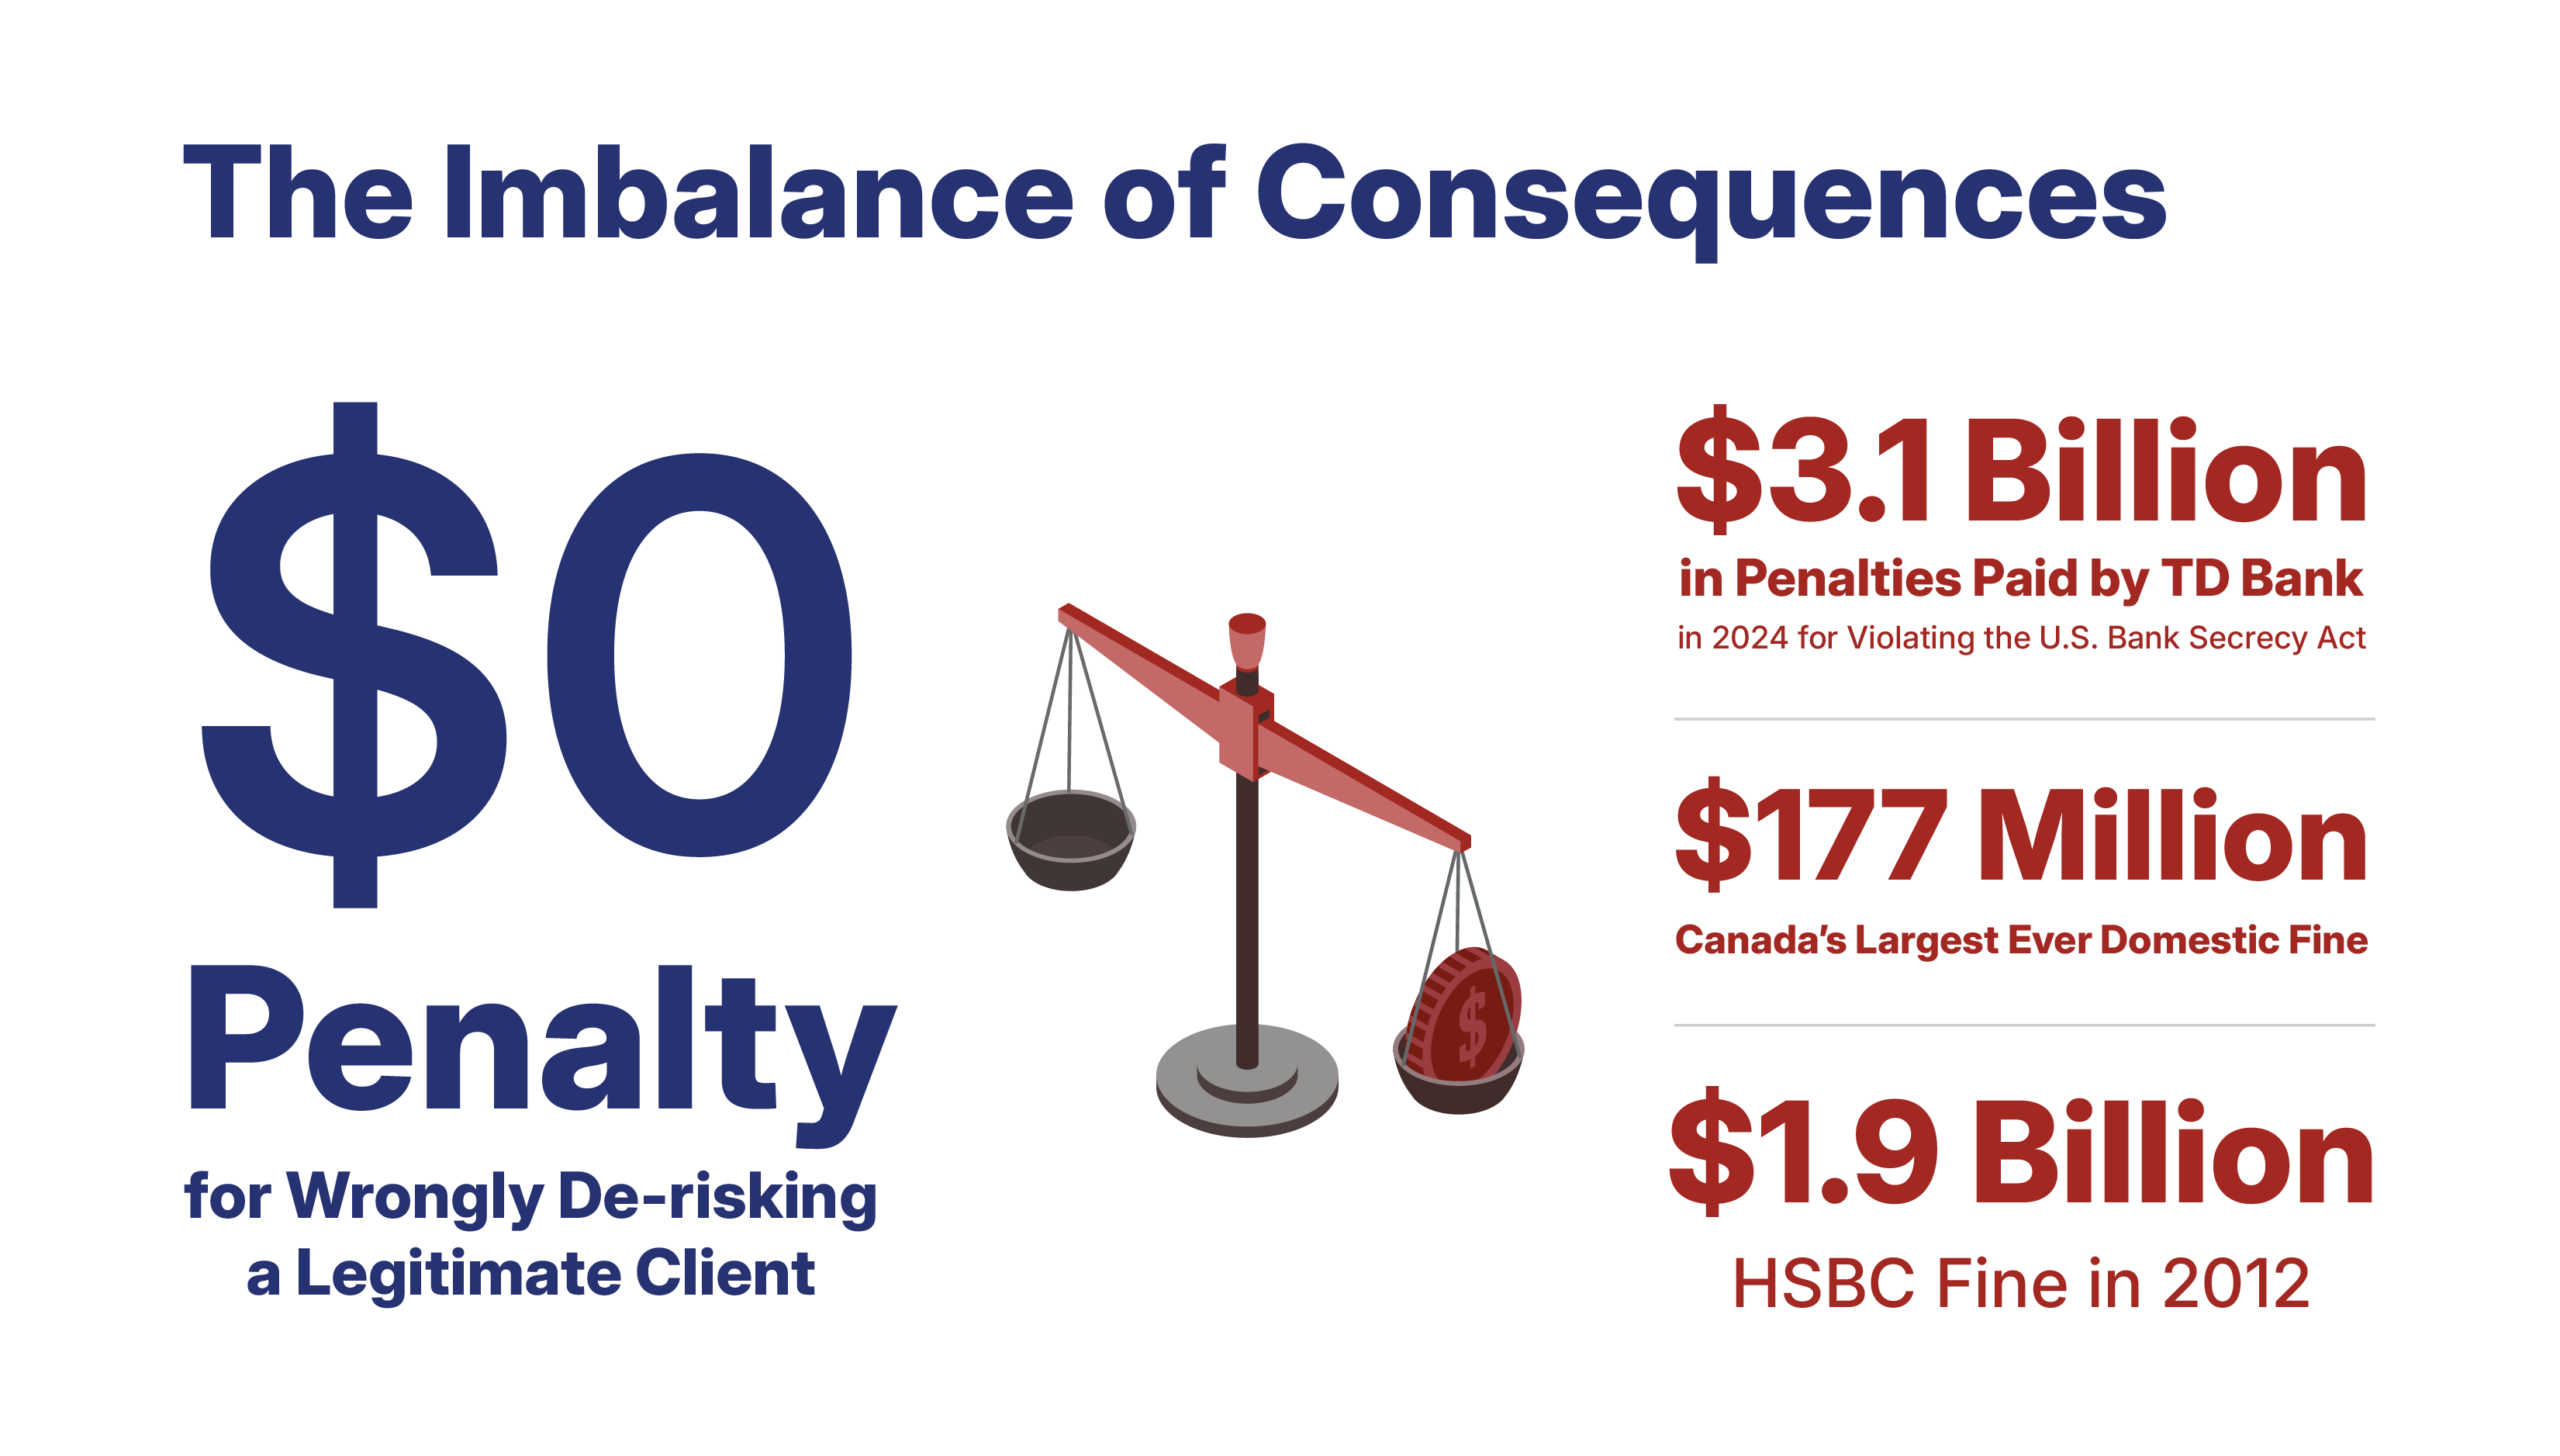
De-risking is produced by an interlocking policy ecosystem, not by decisions made in isolation within bank compliance departments. At its centre is the Proceeds of Crime (Money Laundering) and Terrorist Financing Act, which imposes severe financial and reputational penalties for compliance failures while offering no corresponding cost for wrongly de-risking a legitimate client. Combined with ambiguous “risk appetite” standards and a low regulatory tolerance for error, this creates a stark cost-benefit imbalance in which client exit becomes the rational business choice.

This architecture is reinforced across at least 13 federal departments and agencies, international standard-setters such as the Financial Action Task Force (FATF), and more than 38,000 private-sector reporting entities. A central driver has been Canada’s series of National Inherent Risk Assessments (NIRAs). The 2015 and 2023 assessments consistently framed registered charities as “high risk” for terrorist financing, despite acknowledging that the actual scope of the problem was limited, and despite FATF’s own guidance since 2016 warning against sector-wide de-risking. The 2025 report marks a meaningful shift in tone, renaming it the National Risk Assessment in recognition of mitigation measures NPOs and other sectors put in place, lowering the NPO sector’s classification and explicitly cautioning against bias and unintended consequences. However, this shift does not undo a decade of entrenched institutional risk models and compliance culture built on the earlier framing.

These dynamics are compounded by findings from NSIRA’s 2025 review of the Canada Revenue Agency’s Review and Analysis Division, which found that charity audit decisions were often poorly documented, inconsistently applied, and based on outdated or weak intelligence, creating conditions in which bias could operate unchecked. If a government agency subject to statutory oversight can generate risk assessments of this quality, the report argues, the risks are magnified within banks, where internal decisions are shielded by commercial confidentiality and face no equivalent independent review.

Documented Patterns and Impacts

De-risking in Canada is shown to be a systemic, recurring practice rather than a marginal or theoretical concern. It affects humanitarian charities, faith-based organizations, advocacy groups, frontline aid workers, executives, board members, and their families. Recurring patterns include the treatment of unverified or debunked media allegations as credible risk indicators; the expansion of de-risking beyond banks into payment processors, donation platforms, and customer relationship manager (CRM) systems; and a persistent disconnect between evolving government sanctions or humanitarian exemptions and continued account freezes and other repercussions imposed by financial sector institutions.

The organizations most affected include Muslim-led charities, international humanitarian and development NGOs, and organizations connected to jurisdictions such as Syria, Palestine, or Pakistan. Documented impacts include abrupt account closures and service denials, exclusion from payment processors, operational disruption to humanitarian programs, individual de-risking of employees, board members and their families (including personal credit cards and RRSPs), and lasting reputational harm. These operational impacts translate into profound civil liberties concerns, impacting the right to equality and freedom from discrimination, freedom of association, freedom of expression, and the right to life and security of the person, particularly where de-risking impedes life-saving humanitarian assistance.

Recourse, Oversight, and Accountability Gaps

The report identifies a near-total absence of effective recourse for organizations and individuals subject to de-risking. Financial institutions are not legally required to provide a specific reason for closing an account, and vague references to “risk appetite” are standard practice. The Ombudsman for Banking Services and Investment (OBSI) explicitly excludes complaints relating to a firm’s risk-management practices from its mandate, and the Financial Consumer Agency of Canada (FCAC) cannot address de-risking absent stronger financial inclusion laws. No independent body in Canada has the mandate to review whether a de-risking decision was reasonable, non-discriminatory, or evidence-based, and no authority systematically collects data on the scale or nature of de-risking in Canada. The result is a system in which life-altering financial decisions are made behind closed doors, based on undisclosed criteria, without meaningful appeal.

The report concludes with 12 recommendations to the federal government, supervisory bodies and financial institutions and payment processors. Taken together, these recommendations offer a comprehensive reform agenda: one that recalibrates national ATF policies, strengthens oversight and documentation requirements, closes accountability gaps in the financial sector, and ensures that Canada’s counter-terrorism financing measures do not come at the expense of the civil liberties and financial inclusion of communities they were never meant to exclude.


Summary of Case Studies

The report includes six anonymized case studies, shared with permission, that illustrate how de-risking manifests in practice across the financial system.

Case 1: Impact on Funding

Unverified foreign misinformation leads to a donation processor abruptly de-platforming a charity, followed by a bank’s decision to close its account.

A donation-processing platform notified a large, established humanitarian organization operating in Syria and other countries that it would be off-boarded within fifteen to thirty days, after the platform’s new banking partner made a de-risking decision. No explanation of the underlying risk was given. Recurring donations, a significant funding source, were disrupted, and the charity was forced to diversify payment processors to continue operating, absorbing significant reputational and administrative costs in the process.

Case 2: The Role of Implicit Bias in De-banking Decisions

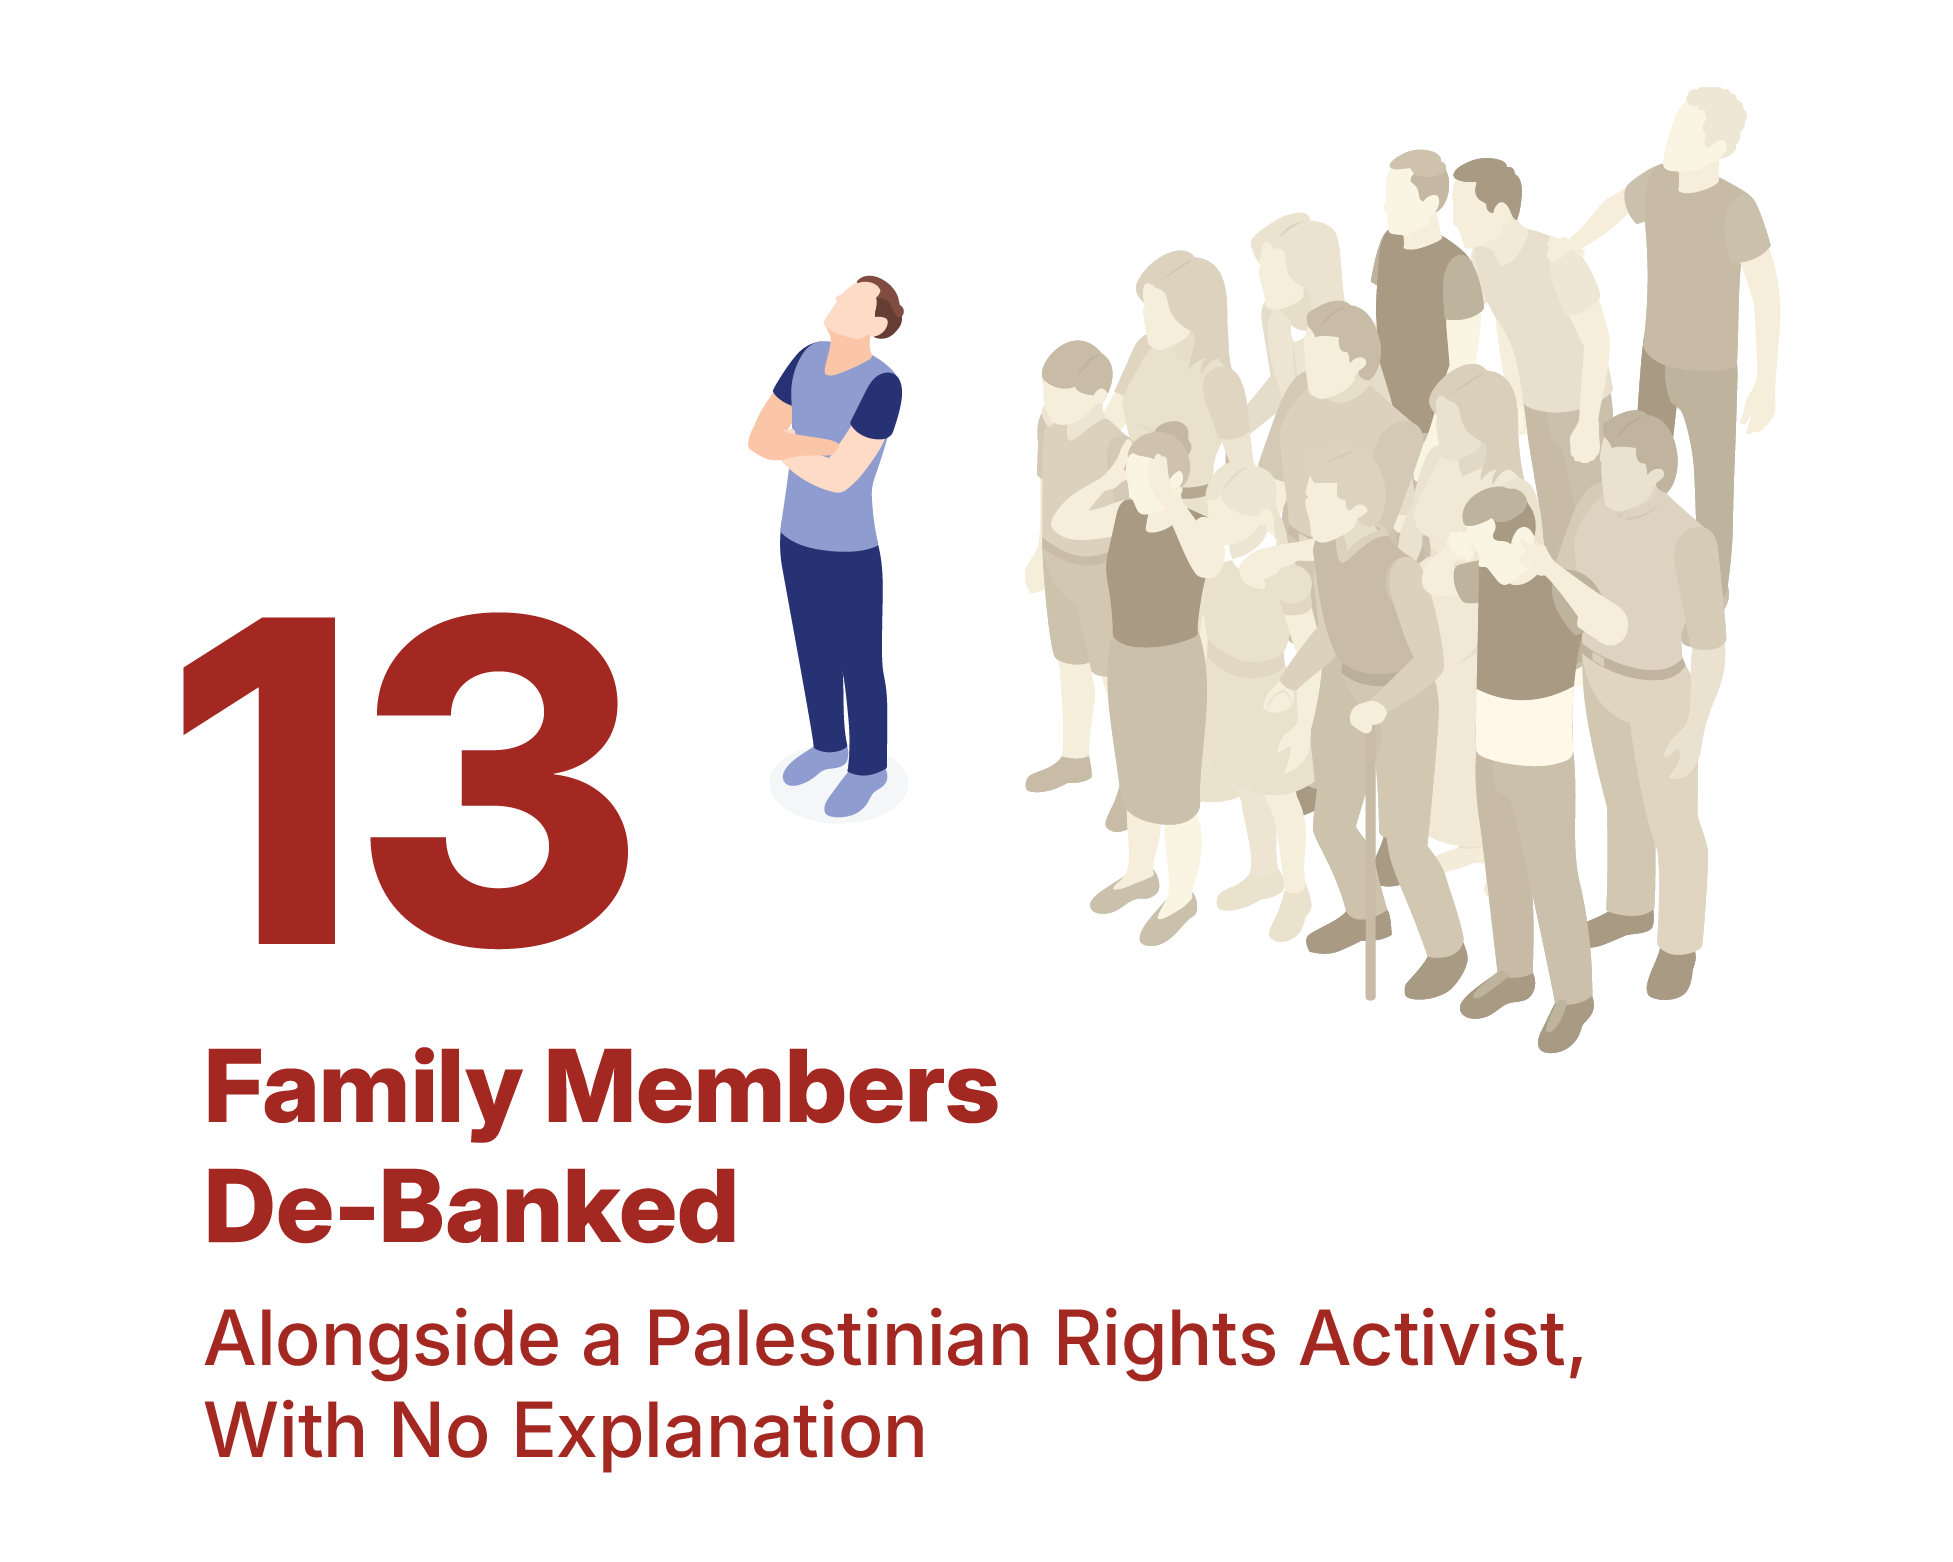
A Palestine solidarity organization, one of their directors and their[1] family are suddenly de-banked

An organization engaged in lawful advocacy for Palestinian human rights was suddenly de-banked in 2024. Shortly after, one of the organization’s directors, who had an account at the same financial institution, was also de-banked, along with thirteen family members. Neither the organization nor the de-banked director were provided with explanations despite repeated requests. The organization was forced to suspend its activities for several months. The director faced missed payments which went to collections, causing significant hardship for elderly parents. Two years later, after the director’s advocacy had ended, a second Canadian institution de-banked them, once again without a specific reason. The case illustrates restrictions on the right to free expression, the effects of guilt-by-association and the absence of any avenue to challenge a de-banking decision.

Case 3: Disconnect Between De-risking and Government Sanctions Lists

A payment processor freezes nearly $1 million after Canada amends its Syria sanctions to permit humanitarian aid.

After Canada’s February 2025 sanctions amendment authorized humanitarian aid to Syria, a charity’s payment processor froze close to $1 million in funds, citing risk concerns and eventually admitting it was unaware of the exemption. Despite being shown evidence of the change, the freeze persisted for nearly a year, and the charity was required to pause its Syria operations as a condition of continued service, only resuming after a Ministerial clarifying statement in April 2026.

Case 4: Collateral Damage to Families and Financial Ecosystems

A domestically operating Muslim-led charity and its executives are de-banked following a since-retracted news article.

A Canadian charity with no international operations lost its banking relationships after a news article falsely linked it to terrorist entities. Despite the article’s later retraction, multiple banks also closed the personal accounts, RRSPs, and credit cards of a charity executive and their spouse, with no explanation offered until an informal disclosure two years later. Recourse to bank ombudspeople and a third-party risk-screening company produced no answer or remedy, and residual impacts, including further card cancellations, continue today.

Case 5: Opaque Internal Practices of AML/ATF Compliance Units

A charity is de-banked by a credit card company a week after enthusiastic onboarding, and no executive can explain why.

A charity’s application for credit card services was welcomed and expedited by account managers, only for the account, and associated donation processing, to be suspended without warning a week later. Even a senior C-level executive, sympathetic to the charity’s situation, was not authorized to access or override the reasoning of the company’s AML/ATF compliance unit, illustrating how such units function as a sealed “black box” beyond internal executive oversight.

Case 6: Impact on Donors

Intrusive scrutiny of a $400,000 donation leads a donor to withdraw funding entirely.

A Muslim-led humanitarian organization operating in Syria and Palestine had a $400,000 private donation flagged by its bank nearly six months after receipt, despite the charity’s history of comparable donations. A roughly fifty-question inquiry into the donor’s financial affairs, with no explanation of the underlying concern, led the donor to question the charity’s legitimacy and withdraw the gift. The charity has since stopped accepting international donations to avoid a repeat occurrence. 


Summary of Recommendations

The report sets out twelve recommendations directed at three groups of stakeholders: the Government of Canada, supervisory bodies, and financial institutions and payment processors.

Government of Canada

Recommendation 1: Integrate civil liberties and financial inclusion impact analyses into National Risk Assessments (NRA). (Department of Finance)

Recommendation 2: Issue policy guidance to relevant departments and bodies on de-risking and financial inclusion, including reporting requirements. (Department of Finance, Public Safety Canada, Global Affairs Canada, Minister of National Revenue)

Recommendation 3: Amend the PCMLTFA to require reporting entities to report annually on de-risking, including volumes and rationale. (Department of Finance)

Recommendation 4: Amend the PCMLTFA to clarify that failing to safeguard against disproportionate de-risking constitutes a compliance failure. (Department of Finance)

Recommendation 5: Integrate the non-profit sector into AML/ATF policy-making, particularly the NRA drafting process, through a clear, resourced consultation strategy. (Department of Finance)

Recommendation 6: Develop guidance to help the private sector correctly interpret and apply changes in sanctions and counter-terrorism financing policy. (Department of Finance, Public Safety Canada, Global Affairs Canada)

Recommendation 7: Strengthen government consultation with NPOs and cross-sector exchange between NPOs and the financial sector, including through the ACMLTF. (Department of Finance)

Supervisory Bodies

Recommendation 8: Issue coordinated guidance emphasizing risk mitigation over client exit, including practical examples and treatment of sector-wide de-risking as a compliance deficiency. (FINTRAC, FCAC, OSFI)

Recommendation 9: Require minimum documentation standards for risk-based decision-making. (FINTRAC, OSFI)

Recommendation 10: Develop training on risk-based decision-making regarding the NPO sector, including systemic bias and discrimination. (FINTRAC, Department of Finance)

Recommendation 11: Allow independent review of financial institutions’ risk-based decision-making in complaint investigations. (OBSI)

Financial Institutions and Payment Processors

Recommendation 12: Adopt due process standards for account closures, including clear reasons, a formal opportunity to respond, and an independent internal review mechanism separate from the original decision-maker. (Private sector)

[1] We are using “they/their” to help safeguard the individual’s identity.

The Damage of De-risking: Watch ICLMG’s report launch

Thank you to everyone who were able to attend, we had a great turn-out!

If you missed it, you can watch the recording of the launch above, and read the report below:

“The Damage of De-risking: How Canada’s Policies to Counter Terrorism Financing Drive Financial Exclusion”

What is the report about?

A humanitarian organization providing aid to civilians in Syria and other populations in crisis is suddenly told that their online donation processor would be shutting their account in 30 days, with no explanation. An organization engaging in education and advocacy for solidarity with Palestine has its bank account suddenly shuttered; not long after, one of the organization’s directors and 13 members of their family also have their accounts shut. All with no explanation and no recourse.

This is the reality of de-risking: the practice whereby financial institutions terminate or restrict access to financial services for certain clients or sectors to avoid perceived regulatory, compliance, or reputational risk, rather than managing that risk through proportionate, individualized and evidence-based mitigation measures. This has resulted in unjustified and discriminatory decisions that significantly impact both individual and organizational clients, including non-profits and charities.

Our report shows that the de-risking of non-profit organizations in Canada, particularly those that are active in Muslim communities or carrying out humanitarian activities abroad, is not a series of isolated commercial decisions made by individual banks, but a predictable structural outcome of Canada’s anti-terrorist financing framework.

During the webinar, we presented our analysis of Canada’s anti-terrorist financing ecosystem and its impacts, shared case studies from individuals and organizations who have been impacted by de-risking, and outlined our recommendations to remedy the situation.

ICLMG’s National Coordinator and report author, Tim McSorley, was in conversation with former Special Representative on Combatting Islamophobia, Amira Elghawaby

Speakers:

Tim McSorley is the National Coordinator of the International Civil Liberties Monitoring Group. He joined the coalition in 2016. In 2021, he authored the report The CRA’s Prejudiced Audits: Counter-Terrorism and the Targeting of Muslim Charities in Canada, a precursor to this new report.

Amira Elghawaby is a journalist, human rights advocate, and the Founder and Executive Director of the Muslim Communities Research Observatory. She served as the first ever federal Special Representative on Combatting Islamophobia from 2023 to 2026.


We are very grateful for the support of
The Muslim Fund, whose funding made
this project possible.